
Original Lens and publication context
Trump made seven claims in an hour. Iran's Parliamentary Speaker called all seven false. The tankers proved him right on the water. Sunday's Islamabad talks and Tuesday's ceasefire expiry now carry the whole trade.
- Trump made seven claims in an hour on Friday — Hormuz reopened, an "unlimited" nuclear moratorium, a stockpile handover — and Iran's Parliamentary Speaker called all seven false. Two of three tankers on the neutral route were turned back; only the Iran-sanctioned route passed.
- The energy complex took the full hit: WTI -11.45% to $83.85, Brent -9.07% to $90.38, heating oil -11.36%, dated Brent below $100 for the first time since 11 March. The US 10-year fell to 4.23% and the dollar index erased its war-bid.
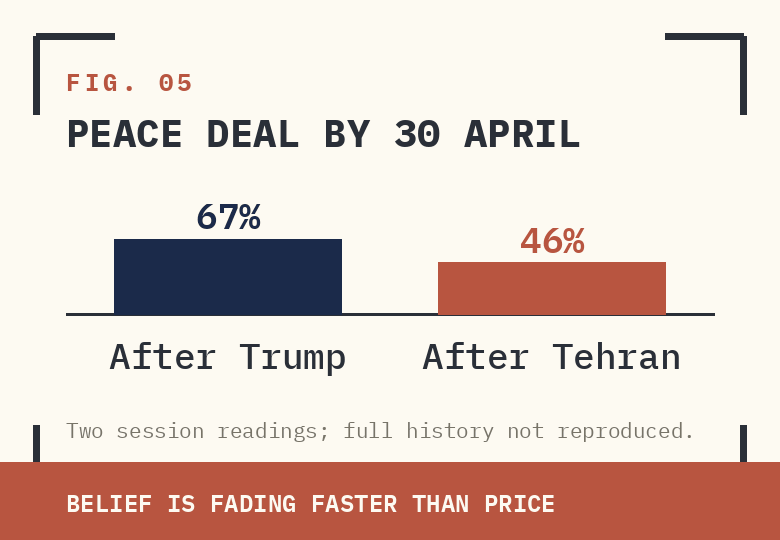
- Belief is fading faster than price: the peace-deal probability contract peaked at 67% after Trump and fell to 46% after Tehran inside the same session, while oil, yields and the dollar have not adjusted. That dislocation has to resolve on Monday.
- Three binaries: Sunday's Islamabad talks (Round 1 failed), Monday's first session without the dealer gamma pin and with residual CTA demand of ~$45–50bn rather than $70bn, and Tuesday's ceasefire expiry. The market is priced for a signed extension; almost nobody is positioned for combat resuming.
- Position: do not fight the residual bid but size down, trim crowded right-tail calls and rotate into OTM put spreads on the dozen index-leaders. Oil hedges — a long-dated Brent call spread or energy-ETF call — are at their cheapest since the war began.
01 | THE SETUP
- The move. WTI -11.45% to $83.85. Brent -9.07% to $90.38. Heating oil -11.36%. Dated Brent below $100 — first time since 11 March. 10Y to 4.23%. The dollar index erased its war-bid. Equity futures green.
- The driver. Trump Truth Social flurry + a phone interview with the financial press: Hormuz reopened, moratorium "unlimited," talks "go on over the weekend." Trump personally said "no" to the reported $20bn release.
- The tell. Iran's Parliamentary Speaker Ghalibaf personally called Trump's claims "seven lies in one hour." Two of three tankers on the neutral route were turned back. Polymarket 67% → 46%.
- The catalysts. Sunday — Islamabad talks Round 2 (Round 1 under Vance failed). Monday — first real-flow session post-OpEx. Tuesday — ceasefire expires.
02 | THE FRIDAY TAPE: TRUMP TALKS, TEHRAN DENIES
The pin released a day early. Same Truth Social driver as the ten-session rally — but this time Tehran pushed back hard enough to matter.
WHAT TRUMP CLAIMED
- Iran has "agreed to never close the Strait of Hormuz again."
- Iran will hand over its enriched-uranium stockpile — the "nuclear dust."
- Nuclear moratorium — "unlimited," "no years."
- Second-round talks "probably" this weekend; "most of the main points are finalised." Trump said he "may" travel to Pakistan to sign.
- On the reported $20bn-for-stockpile proposal — Trump repeatedly said "no" in the phone interview. The US negotiating position, publicly disavowed by the President.
- NATO a "Paper Tiger" for not assisting the US Hormuz mission.
Seven assertions, one hour. No signatures, no verifications, no Iranian confirmations. The tape ran anyway.
WHAT TEHRAN SAID
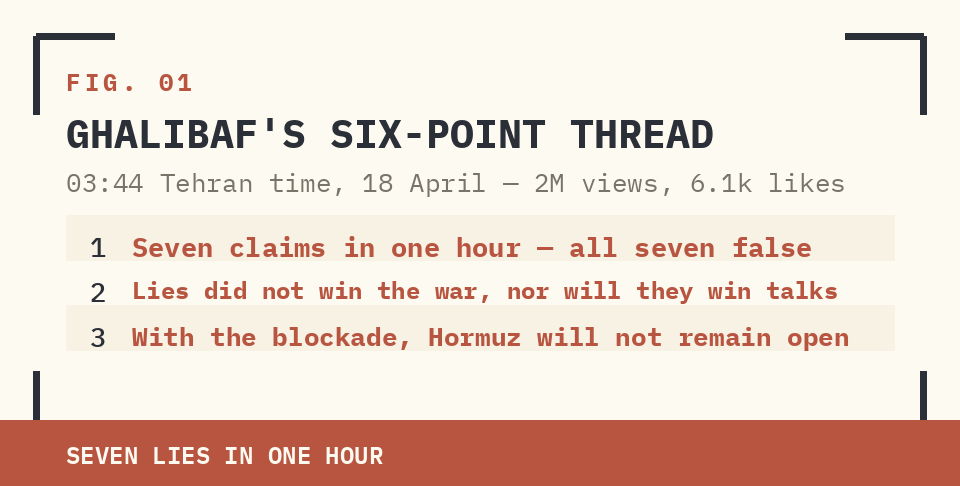
Mohammad Bagher Ghalibaf, Speaker of the Islamic Consultative Assembly (Iran's Parliament), posted a six-point thread at 03:44 Tehran time directly contradicting Trump (2M views, 6.1k likes):
Supplied archive exhibit · original publication context.
- "Seven claims in one hour, all seven of which were false."
- "They did not win the war with these lies, and they will certainly not get anywhere in negotiations either."
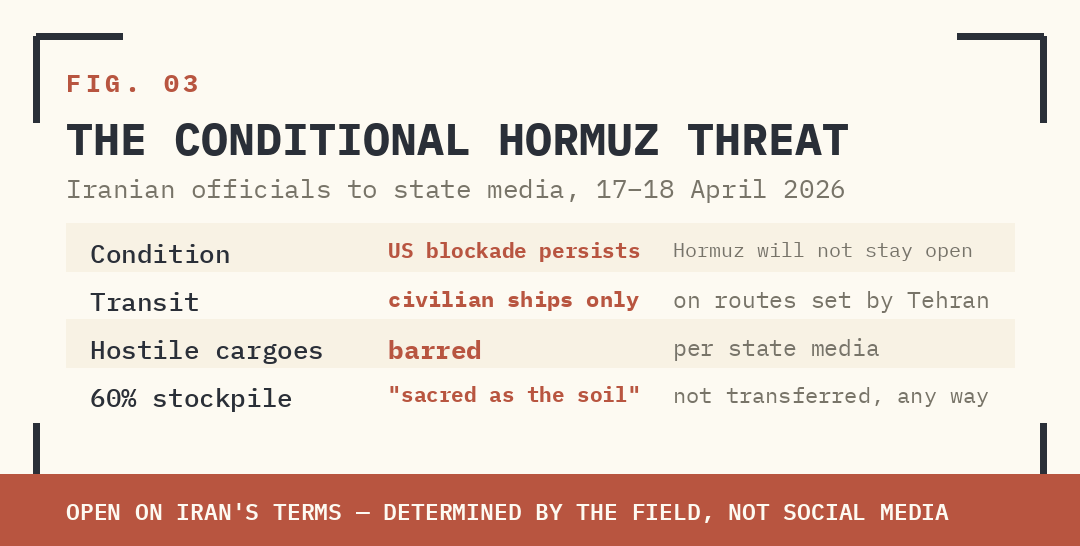
- "With the continuation of the blockade, the Strait of Hormuz will not remain open."
- Transit only via "the designated route" and with "Iranian authorization."
- "Whether the Strait is open or closed and the regulations governing it will be determined by the field, not by social media."
- Directs readers to the Foreign Ministry spokesman's interview for "the real and accurate news of the negotiations."
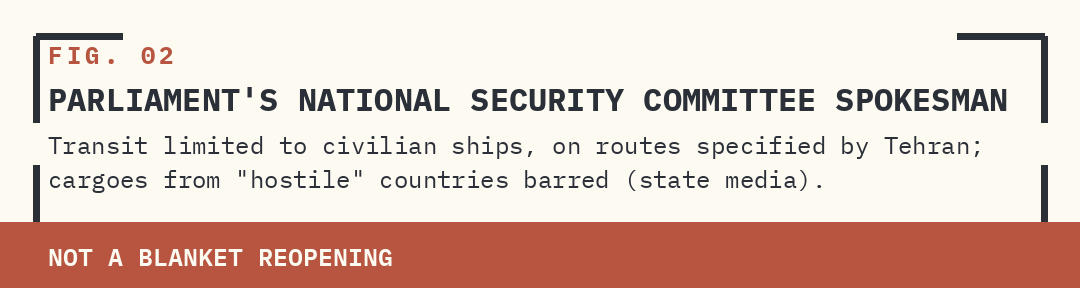
AND FROM LOWER-RANKING BODIES
Supplied archive exhibit · original publication context.
- Transit limited to civilian ships, on routes specified by Tehran — not a blanket reopening.
- Iranian state media: ships and cargoes from "hostile" countries will not be allowed through.
- 60% stockpile is "as sacred as the soil of Iran" and "will not be transferred anywhere under any circumstances" — "in any way" (Foreign Ministry).
Supplied archive exhibit · original publication context.
THE TANKER TEST
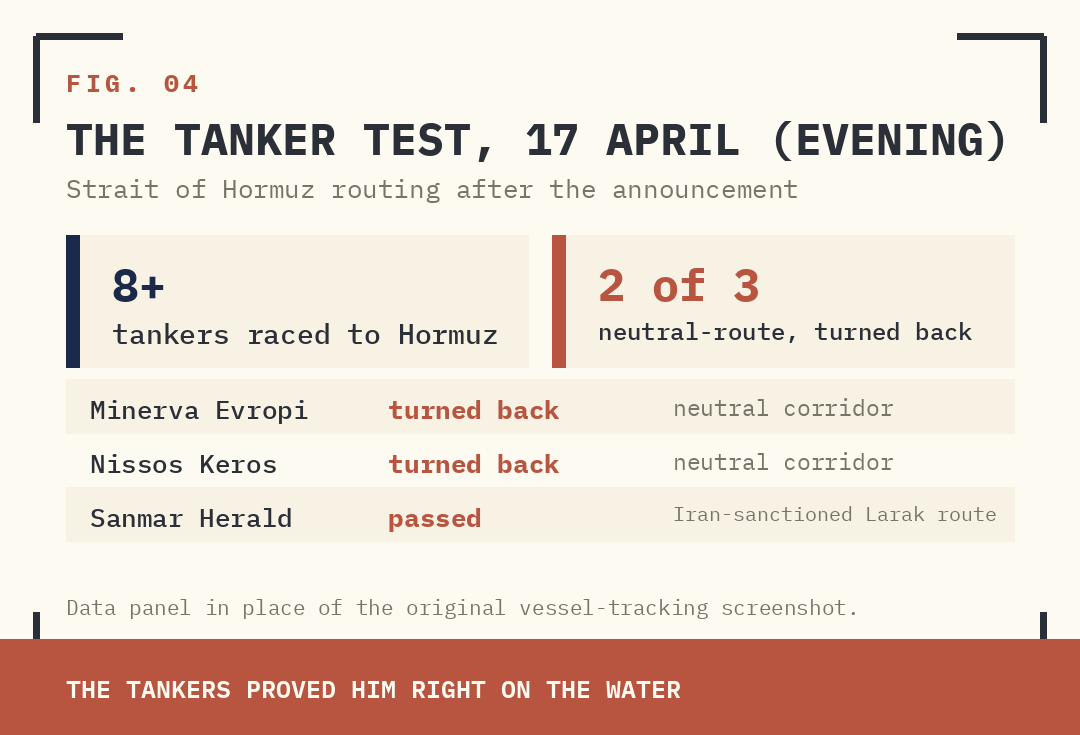
At least eight tankers raced toward Hormuz after the announcement (vessel-tracking data). Of the three with visible routing outcomes:
Supplied archive exhibit · original publication context.
- Minerva Evropi (neutral corridor) — turned back.
- Nissos Keros (neutral corridor) — turned back.
- Sanmar Herald (Iran-sanctioned Larak-island route) — passed.
Ghalibaf called Trump a liar seven times in an hour. The tankers proved him right on the water. The Strait is open on Iran's terms — "determined by the field, not by social media."
03 | THE REPRICING: WHAT MOVED, HOW FAR
The energy complex took the full hit.
INDEX | PRICE | CHANGE | % CHG | CONTRACT |
|---|---|---|---|---|
WTI Crude Oil (Nymex) | 83.85 | −10.84 | −11.45% | USD/bbl May 2026 |
Brent Crude (ICE) | 90.38 | −9.01 | −9.07% | USD/bbl Jun 2026 |
RBOB Gasoline (Nymex) | 300.48 | −15.89 | −5.02% | USd/gal May 2026 |
Natural Gas (Nymex) | 2.67 | +0.03 | +1.02% | USD/MMBtu May 2026 |
Heating Oil (Nymex) | 339.74 | −43.55 | −11.36% | USd/gal May 2026 |
Tbl. 01 — Energy complex close, 17 April 2026. Source: market data.
- Dated Brent (physical) below $100 — first time since 11 March. Futures and physical moved together: the cleaner signal real barrels will transit.
- US 10Y to 4.23%. Term premium from the oil shock unwound. Bonds surged with equities — only coherent if the inflation tail is gone.
- The dollar index erased all war-period gains in one session.
- OIS repriced globally. GBP: -11bp hikes (27.5bp cumul.). ECB: -10bp hikes (44.4bp cumul.). FOMC: cuts now 15bp, down 5bp.
04 | THE $20BN PROPOSAL: WHO IS IN, WHO IS OUT
Per press reporting corroborated by two US officials: a three-page MOU is being negotiated. Trump publicly disavowed the headline financial term within hours.
STRUCTURE OF THE MOU
- Enrichment moratorium. US opener: 20 years. Iran counter: 5. Trump's "unlimited" matches neither.
- Stockpile. Iran surrenders ~2,000 kg, including 450 kg at 60% — the weapons-adjacent fraction that is the reason this talk exists.
- Facilities. Medical-isotope reactors permitted. All facilities above ground. Underground sites out of commission — implicit admission Operation Epic Fury has degraded them.
- Money — contested on the US side. Reported: $20bn frozen-funds release. Trump: repeatedly "no." Sen. Graham: "No JCPOAs on President Trump's watch." The opening bid is being politically boxed in before Iran has responded.
"Neither dismissed nor accepted" is not consistent with "sacred as the soil." Either the public rejection is posture, or the reported MOU is not the deal that will be signed.
05 | POLYMARKET: BELIEF IS FADING FASTER THAN PRICE
Supplied archive exhibit · original publication context.
06 | THE WEEKEND: THREE BINARIES, ONE EXIT
BINARY 1 — SUNDAY: ISLAMABAD TALKS (ROUND 2)
- Momentum. Round 2 is on thin ice — Vance-led Round 1 failed. Any joint readout validates Trump. WTI stays sub-$85.
- Break. "Most of the main points are finalised" becomes indefensible. Oil and yields retrace half of Friday's move by Monday close.
- Postponed. Tehran's framing controls. Polymarket sub-30%. Oil back above $90.
BINARY 2 — MONDAY: THE REAL-FLOW SESSION
- Gamma is gone. Friday's OpEx settled the dealer gamma that pinned SPX at 7,000–7,100. Monday is the first session without that stabiliser.
- Forward CTA demand is smaller than desk estimates. The ~$70bn model was pre-Friday. Friday's tape executed ~25–35% ($20–25bn). Residual: ~$45–50bn over four sessions, not $70bn over five.
- Reversal triggers. CTA sells in scale if SPX closes below 20-day (~6,820) or realised vol expands past trend-model thresholds.
BINARY 3 — TUESDAY: CEASEFIRE EXPIRY
- Signed extension / framework. Base case. Equities grind, oil fades toward $70, oil-stocks decoupling resolves.
- Tacit extension, no paper. Status quo without document. HYG lags harder; breadth deteriorates; index holds.
- No extension, combat resumes. Oil to triple digits in two sessions. The $86bn CTA buy reverses. 0DTE unwinds violently. The dozen index-leaders become the exit door.
The market is priced for Scenario 1. Options are hedging Scenario 2. Almost nobody is positioned for Scenario 3.
07 | BUY SIDE LENS VIEW: POSITIONING INTO MONDAY
POSITION
- Don't fight the residual bid — size down. ~$45–50bn remaining is less than half of what has already been executed.
- Trim right-tail calls. SPX skew above its four-year cap; trade is crowded.
- Rotate into OTM put spreads on the dozen index-leaders — widest price-to-200-day gap is where unwinds start.
HEDGE
- Oil hedges at their cheapest since the war: WTI $83.85, Brent $90.38, dated Brent sub-$100, vol collapsing, curve -70% of war premium.
- Long-dated Brent call spread or energy-ETF call is asymmetric into Scenario 3. Priced against war-is-over; paid if the market is wrong.
WATCH
- HYG. No new high Friday. Divergence vs SPX widened. Credit leads.
- Dated Brent. Front-to-back spread tells you if the physical market believes Hormuz stays open past a week.
- Prime brokerage CTA data. Confirms Friday-executed vs residual split. Precedent is constructive — but precedent does not assume a single Truth Social feed is the only load-bearing input.
The price action believes Trump. The probability markets have started to believe Tehran. Monday is when those two prices have to meet.


