
Original Lens and publication context
Three sessions of derivative data tell a complete story: a geopolitical headline shook out a thin slice of the short base, retail stepped in to amplify the move, and by Thursday the bears were back adding positions.
- FII index-futures short open interest closed 9 April at 3,06,724 contracts — 91.5% of the 3,35,203 base is intact. Only 25,398 shorts were closed on the 8 April rally.
- The 8 April cover was real but thin: FII bought 32,035 net index futures, yet total FII derivative volume was 5.4× lower than Monday and retail's share of volume jumped from 32.4% to 40.8% — momentum amplification, not institutional accumulation.
- Thursday confirmed it: FII sold stock futures net (–8,593 lots), aggregate market OI expanded on both the rally (+1.63%) and the selloff (+1.88%), and FII put longs hit 8,00,192 with the put/call ratio at 1.73× — the hedge is fully reinstated.
- Rates are the north star. Crude settling above consensus keeps inflation sticky and the RBI constrained; any equity rally built on re-accelerating cuts rests on fragile foundations.
- Base case for the next 48 hours is range-bound into the 10 April talks; visible disagreement on Hormuz would unwind optimism faster than it was built. The downside view belongs in options structures. Regime reassessment needs short OI sustained below 2,50,000 contracts.
3,06,724 FII INDEX FUT SHORT OI — 9 APR 91.5% of base intact | –25,398 SHORTS CLOSED ON 8 APR RALLY of 3,35,203 base | 1.73× FII PUT/CALL LONG RATIO — 9 APR Hedge rebuilt | 5.4× FII VOLUME COLLAPSE ON RALLY vs 7 Apr baseline | 25 STOCKS ABOVE 80% MWPL 2 in F&O ban |
GEOPOLITICS
The ceasefire already looks more fragile than the market priced in. Talks start 10 April. The Strait of Hormuz remains unresolved — and as long as it is, it is structurally irrational for Tehran to allow normalisation of oil flows. That is their only card.
Dec-26 Brent moved back above its prior close even as the front contract fell. The curve is not complacent about the back end. SPR drawdowns need to be replaced. If a managed Hormuz toll becomes structural, that is a permanent change to the global oil cost base — not a temporary disruption. Markets have not begun to price that tail.
India's exposure is specific: a net crude importer, a current account structurally sensitive to oil, a rupee already under pressure, and limited fiscal room to subsidise a prolonged spike. The equity market is treating geopolitical risk as contained. The bond market and the currency are less sanguine.
FLOWS
The risk-reward up here feels poor. But positioning is doing the market's work — and that is worth taking seriously before fading it.
What that number doesn't show: total FII derivative volume on Wednesday was 5.4× lower than Monday. Retail participant market share jumped from 32.4% to 40.8%. That is a momentum-amplification signature, not institutional accumulation. The covering was real. The conviction behind it was not.
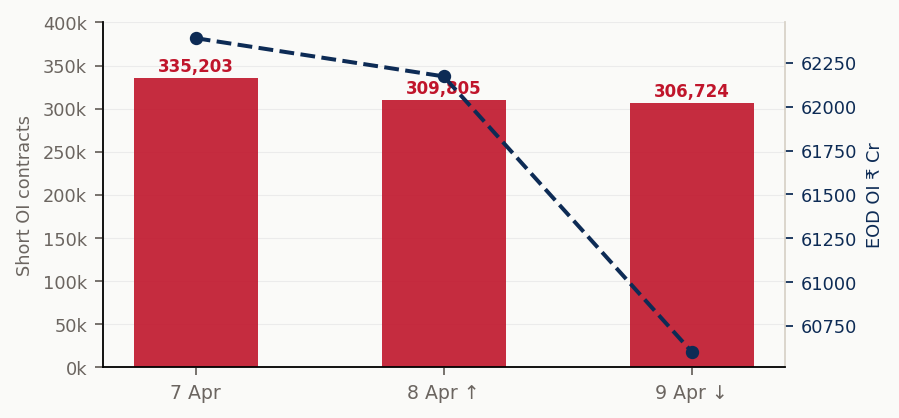 Supplied archive exhibit · original labels. Read alongside the editorial corrections. | 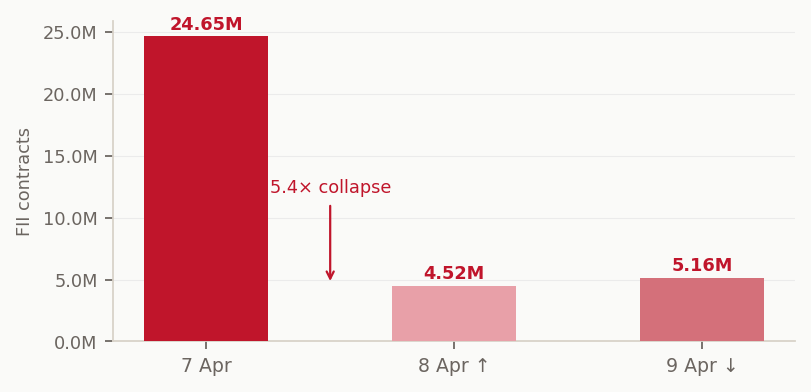 Supplied archive exhibit · original labels. Read alongside the editorial corrections. |
Thursday confirmed the read. FII were net sellers of stock futures (–8,593 lots) with index futures essentially flat (–318). Aggregate market OI expanded on both the rally day (+1.63%) and the selloff day (+1.88%). In a genuine short-cover rally, OI compresses. Two consecutive sessions of expansion mean outstanding contracts increased. Aggregate open interest alone does not reveal whether the initiating flow was predominantly buying or selling.
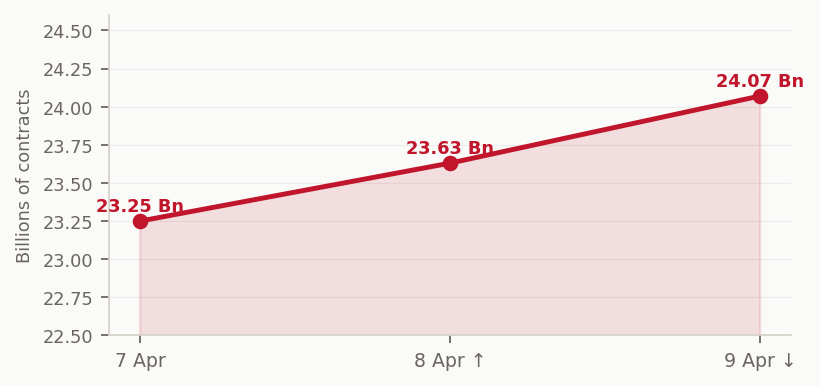 Supplied archive exhibit · original labels. Read alongside the editorial corrections. | 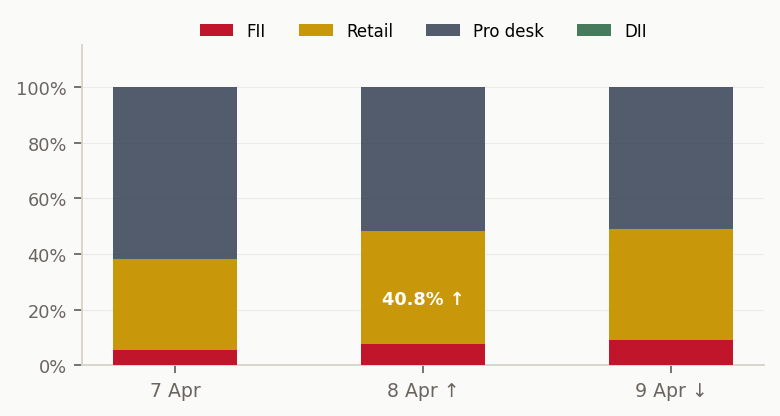 Supplied archive exhibit · original labels. Read alongside the editorial corrections. |
POSITIONING
FII Put Longs hit 8,00,192 on Thursday — the highest in the three-day window. The hedge wasn't unwound. It was briefly trimmed and has been fully reinstated.
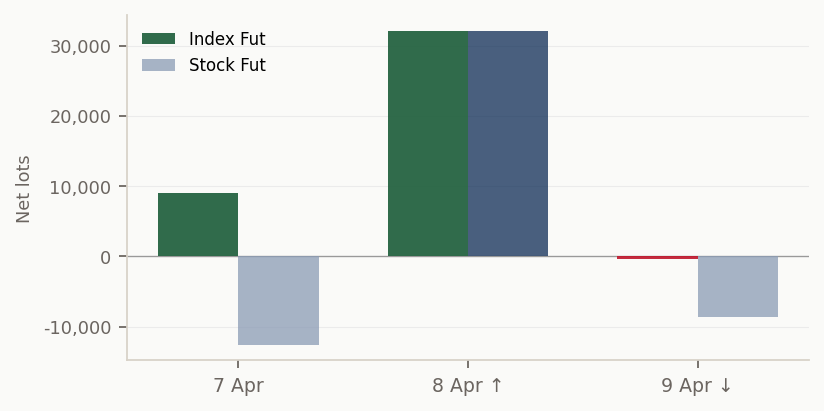 Supplied archive exhibit · original labels. Read alongside the editorial corrections. | 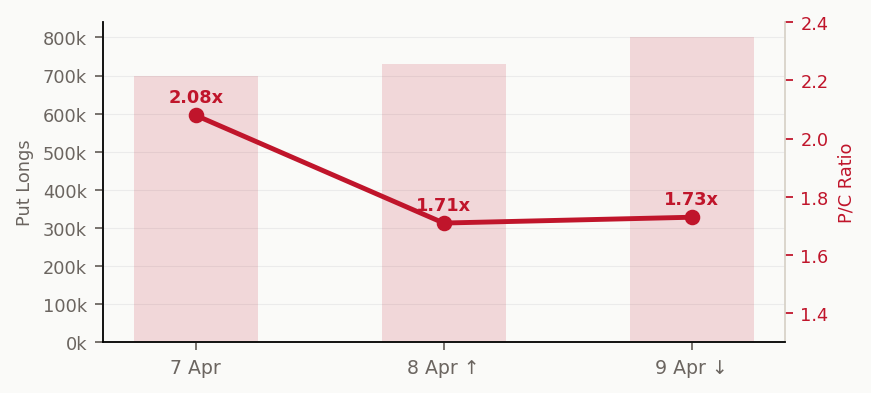 Supplied archive exhibit · original labels. Read alongside the editorial corrections. |
The gross-short in Indian index derivatives was too large going into the event. The covering was mechanical and inevitable once a catalyst emerged — the size of the move was a function of positioning, not of the news itself. That is now substantially complete at the index level.
PARTICIPANT NET OI — LONG MINUS SHORT (ALL SEGMENTS)
FII consistently net long. DII structurally short via portfolio hedging. Millions of contracts.
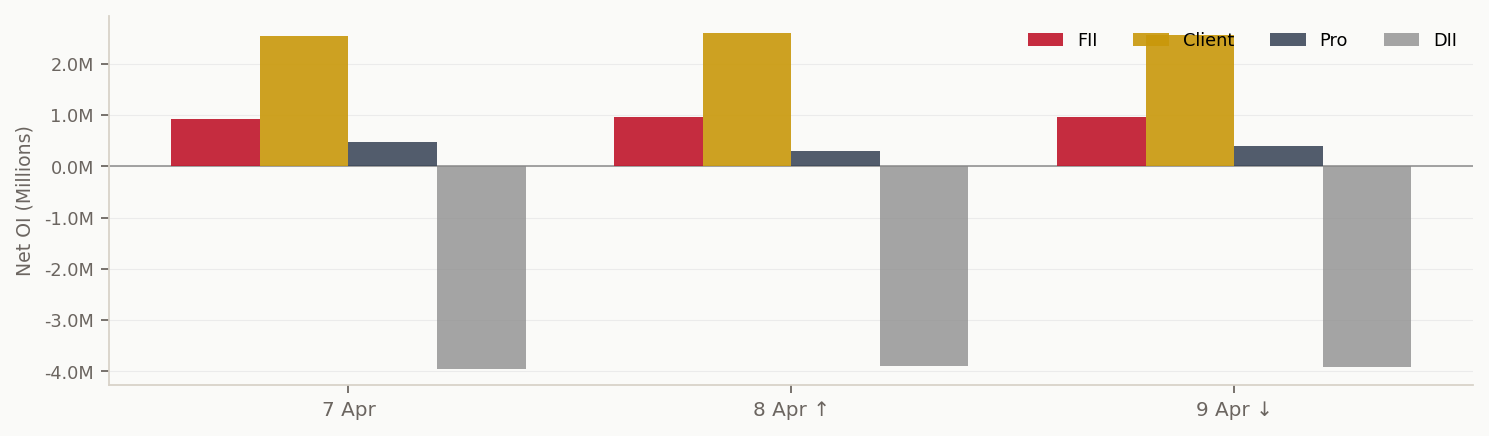
Supplied archive exhibit · original labels. Read alongside the editorial corrections.
RATES & MACRO
Ignore equities for now. Rates are the north star.
The base case before the Iran escalation was already one of sticky inflation and a constrained RBI. The rates distribution that matters is not the tail scenario of aggressive hikes into a full-blown oil shock — that tail has low probability. What is being repriced is subtler: crude settles higher than consensus, refined products stay elevated, growth doesn't collapse, and inflation remains sticky enough that the RBI cannot resume its cutting cycle on the previously expected timeline.
Any equity rally built on re-accelerating RBI cuts is on fragile foundations. The ceasefire removes the acute tail. The chronic tail — oil above consensus, rupee under pressure, fiscal space limited — remains.
RISK
The base case for the next 48 hours is range-bound. Neither side has an incentive to visibly break down before talks begin. But the market has already priced a degree of resolution optimism.
The asymmetric risk is the reverse of what we saw Wednesday. If the 10 April talks produce visible disagreement — particularly around Hormuz transit — the unwind of that optimism will be faster than its build. We have seen this pattern twice in the last six weeks.
There is a tidal wave of technical demand supporting equities in the near term — CTA momentum, short covering mechanics, vol compression. We respect that. But we do not like the level. If vol compression extends far enough, the right expression of the downside view is structures in options, where the cost is compressed and the payoff is asymmetric.
MWPL & BAN LIST
25 stocks above 80% MWPL utilisation. Two in the F&O ban. One name crossed 100% on Thursday. When participants cannot add shorts in individual names, the view gets expressed through options — driving premium and skew higher.
PG ELECTROPLAST 134.3% ABOVE MWPL | RBL BANK 131.0% ABOVE MWPL | SAMMAAN CAPITAL 120.6% F&O BAN | KAYNES TECHNOLOGY 117.9% ABOVE MWPL |
|---|---|---|---|
Jubilant FoodWorks 112.0% Near Ban | Steel Authority of India 105.5% F&O BAN | Exide Industries 102.4% Near Ban | Inox Wind 95.7% Near Ban |
LIC Housing Finance 95.1% Near Ban | Bosch 93.5% Near Ban | Bandhan Bank 90.3% Near Ban | National Aluminium 85.9% Near Ban |
QUICK REFERENCE — 7–9 APRIL 2026
METRIC | 7 APR | 8 APR ↑ | 9 APR ↓ |
|---|---|---|---|
FII Index Fut Short OI | 3,35,203 | 3,09,805 | 3,06,724 |
FII Total Net OI (L–S) | +9,29,859 | +9,71,216 | +9,69,048 |
FII Index Fut Net (lots) | +9,027 | +32,035 | –318 |
FII Stock Fut Net (lots) | –12,584 | +32,065 | –8,593 |
FII Put/Call Long Ratio | 2.08× | 1.71× | 1.73× |
FII Derivative Volume | 2.46 Cr | 45.2 L | 51.6 L |
Retail % of Deriv. Volume | 32.4% | 40.8% | 39.9% |
Aggregate Market OI | 23.25 Bn | 23.63 Bn | 24.07 Bn |
Stocks in F&O Ban | 1 | 2 | 2 |


